Catching Up on 401(k) Math for Late Starters
If you’ve ever looked at your 401(k) balance and felt a little sick to your stomach, you’re not alone.
Maybe you started late. Maybe you changed jobs a few times. Maybe life happened — student loans, rent, kids, a medical bill, a layoff, just trying to keep up. And now you’re staring at retirement advice that seems to assume you’ve been investing since college.
That can feel discouraging fast.
But here’s the good news: you do not need to be a “math person” to catch up. You just need a simple framework, a few key numbers, and a plan you can actually stick with. That’s what catching up on 401k math for late starters is really about: not perfection, not shame, just smart steps from here forward.
This article breaks down the investing math behind a 401(k) in plain English so you can understand what matters, what doesn’t, and what to do next.
First, let’s take the pressure off
If you’re behind, the urge is usually to do one of two things:
- panic and freeze
- panic and throw a random percentage into your 401(k) without understanding it
Neither helps.
A better approach is to understand the basic levers:
- how much you put in
- how much your employer adds
- how long the money has to grow
- how much the money earns
- how much fees take away
That’s it. Most 401(k) math comes down to those five things.
Think of your retirement account like a snowball rolling downhill. The earlier the snowball starts, the longer it has to pick up snow. If you started late, your snowball has less time — but it can still grow. You just need to give it a little more push.
The 401(k) in one sentence
A 401(k) is a retirement account that lets you invest part of your paycheck before taxes, so your money can grow over time.
If your employer offers a match, that’s basically free money they add when you contribute enough to qualify.
That employer match is one of the easiest wins in personal finance. If you’re catching up, this should be one of your first priorities.
The real math: what actually moves the needle?
When people talk about investing math, they often make it sound complicated. But for a late starter, the math is simpler than the feelings around it.
Here’s the plain-English version:
1. Your contributions matter
This is the money you put in yourself.
If you invest:
- $200 per month, that’s $2,400 per year
- $500 per month, that’s $6,000 per year
- $750 per month, that’s $9,000 per year
Those numbers are important because your savings rate affects everything else. If you’re starting later, increasing your monthly contribution is one of the most powerful moves you can make.
2. Time matters more than timing
This is the part that stings for late starters, because time is the one thing you can’t rewind.
But you can still use the time you have.
If your money earns a return and keeps compounding, it can grow much more than the amount you contributed. That’s the snowball effect.
Let’s keep it simple:
- you put in money
- it earns returns
- those returns start earning returns too
- growth builds on growth
That’s compound growth, and it’s the engine behind long-term investing.
3. Employer match is extra lift
If your employer matches 50% of your contribution up to 6% of your salary, that means they’re adding half of what you put in, up to a limit.
Example:
If you earn $60,000 and contribute 6%, you put in $3,600 for the year. If your employer matches 50%, they add $1,800.
That’s $1,800 you didn’t have to earn through extra work.
If you’re catching up, this is huge. The match is like getting a head start in a race you feel late to already.
4. Fees quietly eat returns
Fees are the charges you pay to own and manage your investments. They can be tiny-looking numbers, like 0.04% or 1%, but over time they matter.
A fee is like a leak in a bucket. If the bucket has to stay full for decades, even a small leak can make a difference.
This is why low-cost funds often matter so much in 401(k) investing. You want as much of your growth working for you as possible.
5. Your investment mix affects growth and risk
Your “mix” means how your money is spread across stocks, bonds, and cash-like investments.
- Stocks = ownership in companies, usually more growth but more ups and downs
- Bonds = lending money, usually steadier but lower growth
- Cash-like investments = very safe, but usually don’t grow enough for long-term goals
If you’re trying to catch up, you usually need enough growth to make progress. That often means having a meaningful stock allocation, depending on your age, risk tolerance, and timeline.
A simple example: what late starting can still look like
Let’s say Sam is 38 and just started contributing seriously to a 401(k). Sam earns $60,000 and contributes 10% of salary, or $6,000 per year. Their employer matches 4%, adding another $2,400 if Sam contributes enough to get the full match.
That means:
- Sam’s own contribution: $6,000
- Employer match: $2,400
- Total going into the account each year: $8,400
Now imagine that money grows over time. If Sam keeps contributing regularly and the investments grow at a reasonable long-term rate, the account can still become substantial.
The point isn’t to pretend starting late doesn’t hurt. It does. But it doesn’t make the goal impossible.
That’s the emotional shift a lot of late starters need: not “I’m doomed,” but “I need a stronger plan from this point on.”
How much do you actually need to save?
This is where a lot of people get stuck, because there’s no one perfect number. But there are a few helpful benchmarks.
Start with the match
If your employer offers a match, aim to contribute at least enough to get the full match first.
Why?
Because it’s the highest immediate return most people can get.
If your company matches up to 4% and you’re not contributing enough to get it, you’re leaving part of your compensation on the table.
Then move toward 10% to 15%
A common rule of thumb is saving 10% to 15% of your income for retirement, including employer contributions.
If you started late, you may need to aim higher than someone who started at 22. That’s not a moral failing. It’s just math.
Here’s a simple way to think about it:
- starting early: lower monthly contributions can still work
- starting later: you may need higher contributions and more consistency
If 15% feels impossible today, don’t use that as a reason to quit. Use it as a target to work toward in steps.
Increase in small jumps
If you can’t jump from 6% to 15%, try this:
- go from 6% to 7%
- then 8%
- then 9%
Even a 1% increase can matter more than it sounds like, especially if your raises help cover the difference.
Many people never notice a 1% increase in their take-home pay enough to miss it, but over time it can make a real difference in retirement savings.
The late starter’s advantage: urgency
This may sound odd, but starting late can create clarity.
When you’re early in your career, retirement can feel abstract. When you’re behind, the goal becomes visible, which can motivate action.
You don’t have the luxury of wasting years on indecision, and honestly, that can be helpful.
Instead of chasing every financial trend, focus on the basics:
- contribute enough to get the match
- automate your contributions
- choose low-cost investments
- increase savings whenever you can
- avoid unnecessary fees and panic moves
That’s the backbone of good investing math.
How to think about growth without getting lost in formulas
You do not need to memorize compound interest equations to make good decisions.
Instead, use this mental model:
What grows fastest is money that is invested early, regularly, and cheaply.
That means you want three things working together:
- early enough: start now, not someday
- regularly: invest every paycheck
- cheaply: keep fees low
Let’s say you have two people:
- Person A starts at 25 and invests smaller amounts
- Person B starts at 40 and invests more aggressively
Person A has more time. Person B has less time but may still catch up by contributing more.
That’s the key insight: time and savings rate can partially offset each other.
You can’t change the past, but you can change how hard your money works from now on.
The most common 401(k) mistakes late starters make
If you’re trying to catch up, avoid these traps.
1. Waiting for the “perfect” moment
There’s no perfect week to start, rebalance, or increase contributions.
Markets go up and down. Life is messy. The perfect time never arrives.
What matters is making a good decision and letting time do the heavy lifting.
2. Keeping too much in cash
Cash feels safe because it doesn’t bounce around like stocks do. But for long-term retirement money, cash can quietly lose ground to inflation.
Inflation is just the rise in prices over time. In plain English: the same dollar buys less later.
If your 401(k) is sitting in low-growth options for decades, it may not keep up with your future costs.
3. Chasing recent winners
It’s tempting to move money into whatever fund did best last year.
But short-term winners are not a reliable retirement plan. Good investing math is boring in the best way: steady, diversified, low cost.
4. Ignoring fees
A fund with a 1% expense ratio may not sound expensive. But over many years, it can take a meaningful bite out of growth.
If your plan offers similar options, lower-cost funds are often the better long-term choice.
5. Panicking during market drops
Markets fall sometimes. That’s normal, even though it never feels normal in the moment.
If you sell when prices are down, you can turn a temporary dip into a permanent loss.
For long-term money, a downturn is usually a reason to stay the course, not abandon it.
How to choose investments if you’re behind
For a lot of late starters, the biggest fear isn’t just “am I saving enough?” It’s “what do I even invest in?”
If that’s you, keep it simple.
Use your plan’s target-date fund, if it’s decent
A target-date fund automatically adjusts over time. You pick a fund close to the year you expect to retire, and it gradually becomes more conservative as you age.
Why people like them:
- simple
- diversified
- low effort
- designed for long-term investing
For many beginners, this is a very reasonable option.
Or build a simple diversified mix
If you prefer to choose your own funds, aim for broad diversification.
Diversification means spreading your money across many investments instead of putting it all in one place. Think of it like not putting all your eggs in one basket.
A simple mix might include:
- a U.S. stock fund
- an international stock fund
- a bond fund
You don’t need a dozen funds to be smart. Simpler is often better.
Match your risk to your timeline
If retirement is 25 years away, you may be able to handle more stock exposure than someone retiring in 3 years.
If retirement is closer, you might want a more balanced mix to reduce big swings.
There’s no one-size-fits-all answer, but the important point is this: the mix should support your goal, not make you so nervous that you bail out at the first drop.
A practical catch-up plan for late starters
Here’s a straightforward way to approach catching up on 401k math for late starters.
Step 1: Get the full employer match
Before doing anything fancy, confirm your match rules and contribute enough to receive all of it.
If the match is 4%, 5%, or 6%, that’s your first target.
Step 2: Turn on automatic contributions
Automation removes decision fatigue.
When the money comes out of your paycheck automatically, you’re less likely to talk yourself out of investing every month.
This is especially helpful if you’re overwhelmed by financial noise.
Step 3: Increase your contribution rate by 1% to 2%
If you can’t make a big jump, make a small one.
A little increase can be easier to absorb than you think, especially after raises or bonus months.
Step 4: Choose low-cost, diversified investments
Keep it simple and avoid overcomplicating your 401(k) with too many overlapping funds.
If your plan offers a target-date fund or broad index funds, those are often a solid place to start.
Step 5: Review fees and fund options once a year
You do not need to obsess over your account. But once a year, take 15 to 30 minutes to check:
- am I getting the full match?
- are my fees reasonable?
- is my investment mix still appropriate?
- did my contribution rate increase this year?
That’s enough for most people.
Step 6: Raise your savings when your income rises
If you get a raise, bonus, or debt payment freed up, consider directing part of that money to your 401(k).
This is one of the easiest ways to catch up without feeling the squeeze too hard.
A quick reality check on the numbers
Sometimes late starters ask a painful question: “Can I really make up for lost time?”
The honest answer is: maybe not fully, but you can absolutely make meaningful progress.
You may not reach the exact same balance as someone who started 15 years earlier with the same salary and savings rate. That’s okay. Your goal isn’t to win an imaginary race.
Your goal is to build enough wealth to support your life.
That may mean:
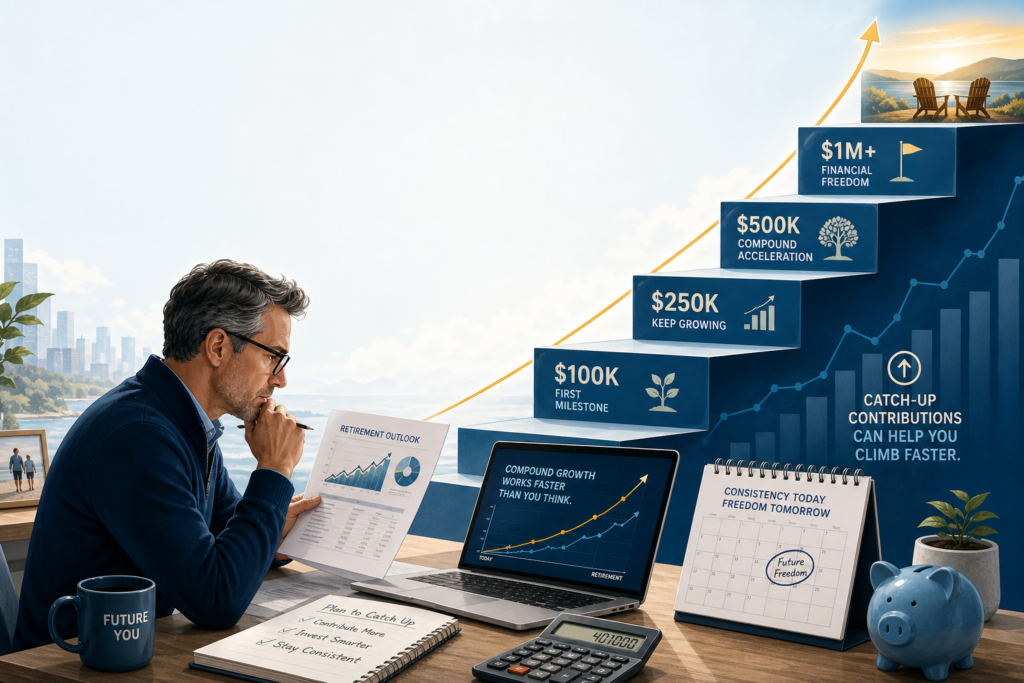
- reaching $10,000 and realizing you can do this
- pushing toward $50,000 and seeing momentum build
- aiming for $100,000 and understanding how the snowball gets stronger
Those milestones matter because they’re proof that the system is working.
And once your balance grows, the math starts to feel different. The market’s gains begin to matter more. Compounding starts to show up in a way you can actually see.
That’s when investing stops feeling like a mystery and starts feeling like a tool.
When the math feels overwhelming, come back to this
If all the charts, percentages, and retirement talk ever makes your head spin, remember this simple version:
- invest enough to get the match
- automate contributions
- keep fees low
- choose a simple diversified portfolio
- stay invested long enough for compounding to work
That’s the heart of investing math.
You don’t need to predict the market. You don’t need to solve for every possible outcome. You just need a repeatable process that moves you forward.
The bigger point: this is about freedom, not perfection
Catching up on 401k math for late starters isn’t really about becoming an expert in finance.
It’s about reducing future stress.
It’s about giving yourself more options later.
It’s about not having to rely on hope, guilt, or vague advice from strangers on the internet.
If you’ve been feeling behind, remember this: starting now still counts. A lot. The next contribution matters. The next raise matters. The next year of consistency matters.
You may be late, but you’re not out.
And once you understand the basic investing math, your 401(k) stops being a source of shame and starts becoming what it was always meant to be: a quiet, automatic system that helps future-you breathe easier.
If you want to keep building confidence, explore more plain-English investing math and retirement basics from InvestMath.
Leave a Reply