The Raise You Got Is Quietly Eating Your Future (And Here’s the Math That Proves It)
You got the promotion. The salary bump felt incredible. You upgraded your apartment, traded in your old car, started ordering takeout a little more often, and booked that trip you’d been putting off for years. You deserved it. Every bit of it.
But here’s a question nobody asked you: where did the extra money actually go?
If you’re like most people earning between $45k and $75k, the answer is a little uncomfortable. The money didn’t disappear into some obvious bad decision. It quietly dissolved into a slightly bigger life. A life that costs just a little more every single month. That process has a name — lifestyle inflation — and it’s one of the sneakiest forces working against your financial future.
Don’t feel guilty about it, though. Seriously. The guilt trip is the last thing you need right now. Lifestyle inflation doesn’t happen because you’re irresponsible. It happens because nobody ever showed you how to calculate the cost of lifestyle inflation before it became a problem. The financial education system failed you long before you ever signed a lease on that nicer apartment.
Here’s the truth: you don’t need to be a math person to understand this. You don’t need a finance degree or a spreadsheet obsession. You just need someone to translate the numbers into plain language, walk you through the real cost of those small upgrades, and show you exactly what to do next. That’s what this article is for.
Whether you’re aiming for your first $10,000 saved, grinding toward $50,000, or trying to figure out what a $100,000 net worth even looks like for someone your age — this math touches all of it. Understanding investing math here isn’t about punishment. It’s about power. Let’s get into it.
What Is Lifestyle Inflation, Exactly? (The Coffee Cup Analogy You’ll Never Forget)
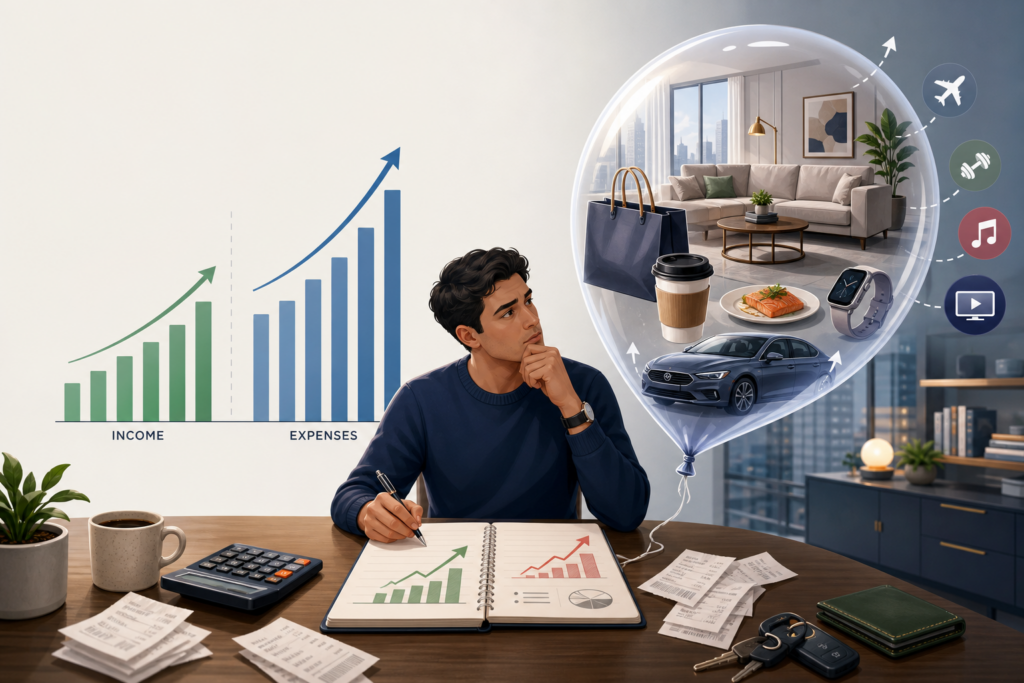
Lifestyle inflation is what happens when your spending rises in lockstep with your income. You earn more. You spend more. Your savings rate stays flat — or worse, it shrinks.
The textbook definition sounds simple. But the lived experience is far more subtle.
Think of your lifestyle like a coffee cup. When you’re earning less, you’re working with a small cup. Your expenses fill it up, your savings overflow the top. When you get a raise, it’s like someone swapped your small cup for a bigger one. And here’s the thing — without even thinking about it, you fill the bigger cup too. Every single time.
The upgrade feels natural. Rational, even. Of course you’d move somewhere nicer when you can afford it. Of course you’d stop eating ramen when real food is within reach. Nobody consciously thinks “I’m going to inflate my lifestyle today.” It just happens, one small, justifiable upgrade at a time.
The dangerous part isn’t any single upgrade. It’s the cumulative weight of all of them. Your streaming subscriptions went from one to four. Your grocery budget crept up by $150 a month. Your gym, your parking, your weekend habits — all of it quietly expanded. The investing math behind this is painfully simple: every dollar you add to your monthly expenses is a dollar that never gets the chance to compound. And compounding is the entire game.
Here’s the core formula to understand what you’re actually losing. Take your monthly lifestyle creep amount — say, $400 extra per month — and ask: what would that become if invested over time instead? That’s the real cost of lifestyle inflation. Not the $400. Everything that $400 could have grown into.
Why This Matters More Than You Think: The Multi-Year Numbers That Should Wake You Up
Here’s where financial education gets real.
Let’s say you’re 30 years old and your income just jumped by $600 a month. You spend all of it. Every month, that $600 vanishes into a bigger life instead of an investment account.
Over 10 years, assuming a modest 7% annual return on investments, that $600 per month would have grown to roughly $104,000. Gone. Not because you blew it on something reckless. Because it quietly funded your expanded normal.
Push it to 20 years? That same $600 monthly investment becomes approximately $314,000. At 30 years? You’re looking at over $680,000. More than half a million dollars — the difference between a funded retirement and a stressful one — just from one single lifestyle creep adjustment that felt completely reasonable at the time.
This is why knowing how to calculate the cost of lifestyle inflation isn’t an abstract finance exercise. It’s the math that sits directly between you and your milestone goals.
Most people think they’ll “catch up later.” They won’t. Not because they’re lazy. Because time is the one ingredient in the compound growth formula you genuinely cannot buy back. Every year you delay is a year the math works against you instead of for you.
The real culprit? It’s not your latte. It’s not your Netflix subscription. It’s the total invisible upgrade — the 15 small decisions that each seemed perfectly reasonable, stacked together into a financial headwind you never calculated. And because nobody taught this in school, most people don’t even realize it’s happening until they’re 45, wondering why their savings account looks nothing like their income would suggest.
The milestone math is brutal here. To hit $100,000 in investments, you need consistent contributions over time. Every dollar redirected to lifestyle instead of investment directly delays that milestone. Not by weeks. By years.
Your 4-Step Action Plan to Calculate and Correct Lifestyle Inflation
You don’t need to white-knuckle your budget or give up everything you enjoy. You need a system. Here it is.
Step 1: Find Your Creep Number
Pull up your bank and credit card statements from 12 months ago and compare them to today. Add up all recurring monthly expenses. The difference between then and now — that’s your monthly creep number. Be honest. Include subscriptions, food delivery, upgraded services, anything that’s changed.
Step 2: Run the Opportunity Cost Math
Take that monthly creep number and plug it into a compound interest calculator. Use a 7% annual return (a reasonable long-term stock market average) and run three scenarios: 10 years, 20 years, 30 years. Write the numbers down. Seeing six figures appear on your screen from what felt like small upgrades is genuinely clarifying. Tools on InvestMath make this kind of investing math accessible without requiring any prior financial education — just plug in the numbers and let the calculator do the heavy lifting.
Step 3: Apply the 50% Rule to Every Raise
Every time your income increases, commit to directing at least 50% of the after-tax increase directly into savings or investments before adjusting your lifestyle. Automate the transfer immediately, the day your new paycheck hits. You still get to upgrade your life a little. But you stop letting the entire raise evaporate.
Step 4: Audit Annually, Not Emotionally
Set a 30-minute “money date” with yourself once a year. Recalculate your creep number. Check your savings rate. Adjust. This isn’t about shame — it’s about staying in the driver’s seat instead of drifting on autopilot.
Frequently Asked Questions
Is lifestyle inflation always bad?
Not at all. Spending more on things that genuinely improve your wellbeing or quality of life isn’t a mistake — it’s the point of earning more. The issue is unconscious inflation: spending more by default rather than by deliberate choice. The goal is awareness, not deprivation.
How do I calculate lifestyle inflation if my income is inconsistent?
Use a 3-month rolling average of both income and expenses. Compare each quarter to the same quarter the previous year. The ratio of expense growth to income growth tells you everything. If expenses are growing faster than income, you’ve got creep.
What if I’ve already been inflating my lifestyle for years? Is it too late?
It’s not too late. It’s never too late. Reducing your creep number even slightly — by $200 or $300 a month — still produces significant compounding over 10 to 20 years. Starting imperfectly today beats starting perfectly in three years.
What savings rate should I actually target?
Most financial experts suggest aiming for a 15–20% savings rate of gross income as a baseline. If you’re starting late, pushing toward 25% accelerates your timeline meaningfully. Any number above zero is a win worth building on.
Keep Going: You’ve Got This
Lifestyle inflation isn’t a personal failure. It’s a predictable response to a system that never gave you the tools to see it coming. Now you have those tools. The math isn’t your enemy — it’s your roadmap.
One honest audit, one automated transfer, one recalculated future. That’s all it takes to start moving the numbers in your direction.
Leave a Reply