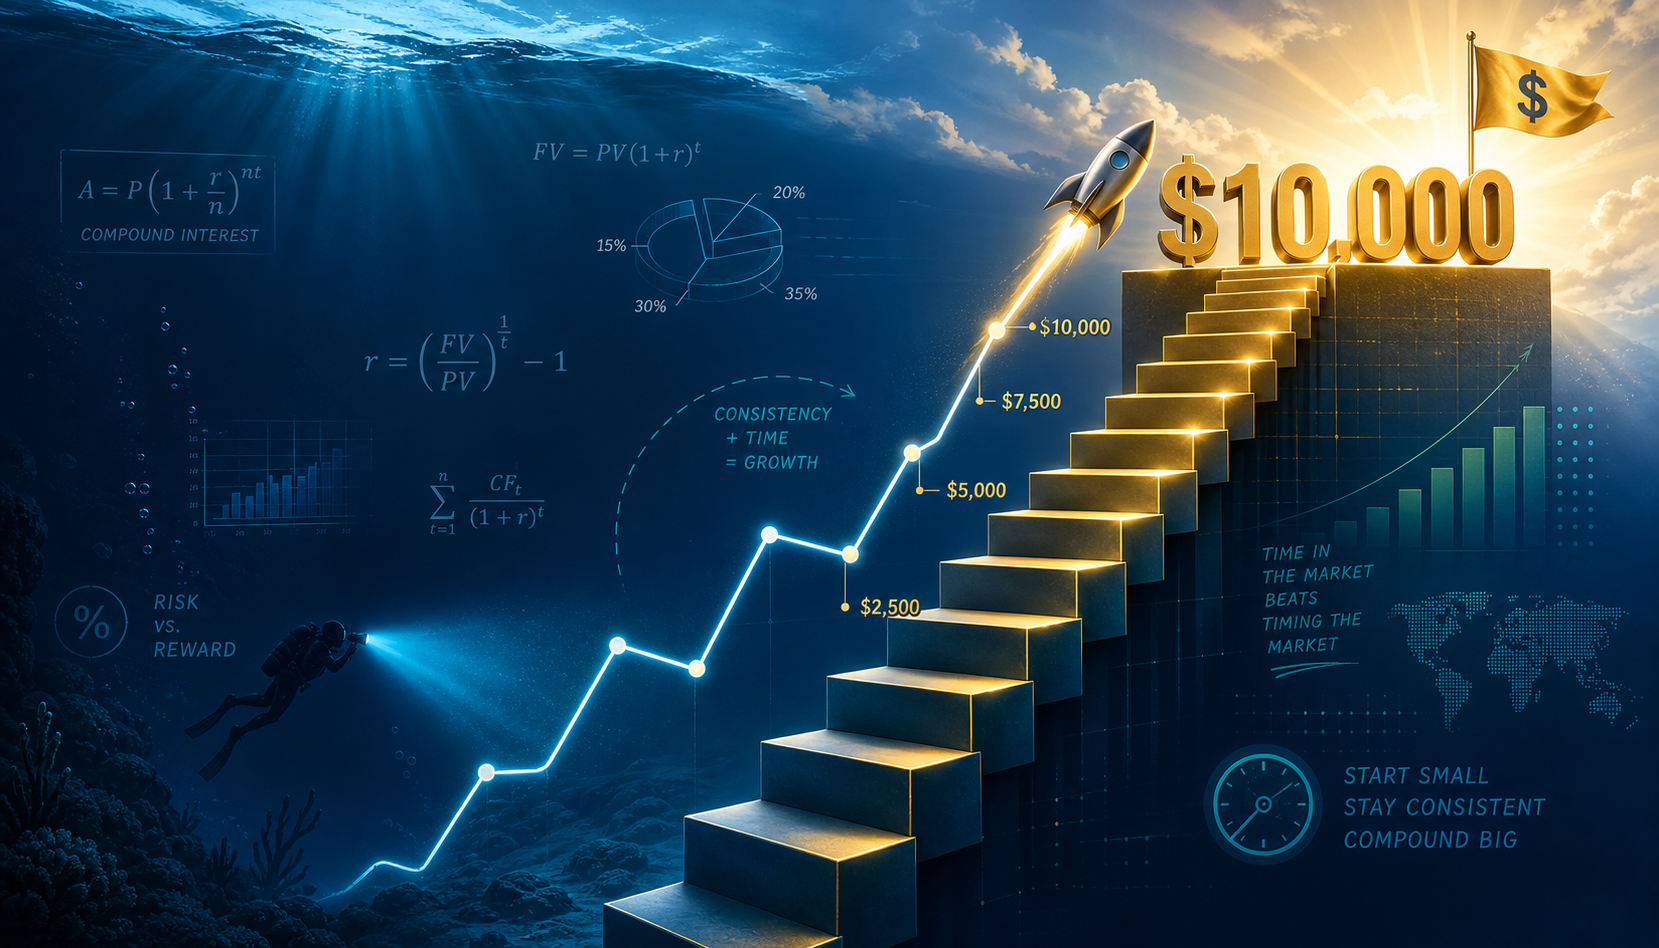
Deep Dive: The First $10,000 Milestone Calculator
If you’ve ever stared at your bank app and thought, “I should be investing, but I honestly don’t even know where to start”, you’re in the right place.
A lot of people feel like investing is something other people learn in a secret clubhouse with spreadsheets and finance degrees. If that sounds familiar, you’re not behind, and you’re definitely not broken. You’re just trying to make sense of a topic that gets wrapped in jargon, hype, and a surprising amount of fear.
That’s exactly why the deep dive the first $10,000 milestone calculator matters.
It’s not just a number-crunching tool. It’s a way to turn vague hopes into something you can actually see, plan for, and work toward. And for a beginner investor, that matters more than it sounds. The first $10,000 is often where investing stops feeling abstract and starts feeling real. It’s the point where your money begins to build momentum instead of just sitting there waiting on you.
Let’s break down what this milestone means, how the math works, and how to use it without needing to become a finance nerd overnight.
Why the First $10,000 Feels So Important
There’s something psychologically powerful about the first big milestone.
For some people, it’s $1,000. For others, it’s $10,000. That number becomes the moment where you stop saying, “I’m trying to invest,” and start saying, “I’m building something.”
Here’s why $10,000 matters:
- It gives you a visible sense of progress.
- It makes investing feel less like a gamble and more like a system.
- It creates a base that can grow faster over time thanks to compounding.
- It helps you build confidence, which is huge if you’ve been nervous about getting started late.
Think of it like rolling a snowball down a hill. At first, it’s small and a little unimpressive. But once it gets enough mass, it starts picking up more snow on its own. The first $10,000 is often that “enough mass” moment.
That’s also why the investing math behind this milestone is so useful. It takes the mystery out of the process.
What the Milestone Calculator Actually Does
A first $10,000 milestone calculator helps you estimate how long it might take to reach your first $10,000 based on three main things:
- How much you start with
- How much you add regularly
- How your investments grow over time
Some calculators also include:
- Expected annual return
- Frequency of contributions
- Compounding schedule
- Fees
- Inflation adjustments
That might sound like a lot, but the idea is simple: the calculator shows how your money can grow when you keep adding to it and let time do some of the work.
This isn’t about predicting the future perfectly. It’s about building a realistic estimate so you can stop guessing.
The Simple Math Behind the Goal
Let’s make the math painless.
There are really only two ways to reach $10,000:
- Save and invest a lump sum
- Build it gradually through regular contributions
Most people do the second one.
Imagine you invest $250 per month. If your investments grow at a modest average rate, you might reach $10,000 in a little over three years. If you invest $500 per month, you could get there in about half that time. If you already have $2,000 saved, the finish line comes sooner.
That’s the magic of combining contributions with growth.
Here’s the plain-English version of the formula:
Your total = what you put in + what your money earns
That’s it.
The “what your money earns” part is where compounding comes in. Compounding means you earn returns on your returns. So instead of your money growing in a straight line, it starts to curve upward like a snowball rolling downhill.
A Quick Example: Three Different Paths to $10,000
Let’s say three people are starting from different places.
Person A: The starter
- Begins with $0
- Invests $200 per month
- Earns an average of 7% per year
This person might reach $10,000 in roughly 4 years, depending on market conditions and fees.
Person B: The closer
- Begins with $3,000
- Invests $150 per month
- Earns an average of 7% per year
This person could reach $10,000 faster because they’ve already covered part of the goal.
Person C: The aggressive saver
- Begins with $0
- Invests $500 per month
- Earns an average of 7% per year
This person could reach the milestone in about 17 to 20 months.
The point isn’t that one path is “better.” It’s that the calculator shows how much your habits matter. When you can see the timeline, it becomes easier to make a plan that fits your actual life.
Why the First $10,000 Is More Than Just a Number
The first $10,000 is often where confidence starts to grow.
For someone like Anxious Sam, that matters a lot. If you’ve been worried about hidden fees, market drops, or getting started “too late,” the first milestone is a proof point. It says:
- You can do this.
- You don’t need to be perfect.
- You don’t need to know everything.
- Small, consistent actions really do add up.
This is where investing math becomes a tool for calm, not confusion.
When you understand how money grows, you stop feeling like you’re blindly hoping for the best. You start making decisions with a reason behind them.
How to Use a First $10,000 Milestone Calculator
You don’t need to overcomplicate this. Start with the basics.
1. Enter your starting amount
This is the money you already have available to invest.
Maybe it’s:
- $0 because you’re just starting
- $500 from a tax refund
- $2,000 in a savings account you want to put to work
Even a small starting point helps.
2. Add your monthly contribution
This is the amount you can invest regularly without stressing your budget.
For example:
- $50 per month
- $150 per month
- $300 per month
If you’re not sure what’s realistic, start with a number you can sustain even in a bad month. Consistency matters more than impressiveness.
3. Estimate your return
This is where the calculator asks how fast you expect the money to grow.
A simple way to think about it:
- Conservative estimate: lower growth rate
- Moderate estimate: middle-of-the-road growth rate
- Higher estimate: more optimistic, but not guaranteed
If you’re using investing math for planning, it’s usually smarter to use a conservative estimate. That helps avoid disappointment and keeps expectations grounded.
4. Review the timeline
The calculator should show:
- When you might hit $10,000
- How much you contributed
- How much growth came from investments
That split is important. It helps you see whether your progress comes mostly from your own saving habits, market growth, or both.
What the Calculator Can’t Tell You
A good calculator is helpful, but it’s not a crystal ball.
It can’t predict:
- Market crashes
- Recessions
- Sudden life expenses
- Job changes
- Tax changes
- Emotional decisions, like panic-selling
So use the calculator as a planning tool, not a promise.
If you’ve ever felt burned by financial advice that made everything sound guaranteed, this is worth remembering. Investing always involves uncertainty. The goal is not to eliminate risk entirely. The goal is to understand the risk well enough to make informed choices.
That’s one of the reasons the deep dive the first $10,000 milestone calculator is so useful. It gives you structure without pretending to know the future.
Fees Matter More Than People Think
Here’s a sneaky truth: fees can slow you down more than you’d expect.
Think of fees like a leaky bucket. You can keep pouring water in, but if there’s a hole at the bottom, you’ll need more water just to stay on track.
In investing, fees can come from:
- Fund expense ratios
- Account maintenance fees
- Trading fees
- Advisory fees
Even small fees can matter over time because they quietly reduce your growth.
For example, if two portfolios earn the same market return but one charges higher fees, the lower-fee option usually leaves you with more money. That doesn’t mean “free” is always best. It just means you should know what you’re paying for.
A milestone calculator is especially helpful here because it can show how tiny differences add up over months and years.
What to Do If You’re Starting Late
A lot of people feel guilty about starting later than they wanted to.
Maybe you spent your 20s dealing with rent, debt, family responsibilities, or just surviving. Maybe investing felt too intimidating. Maybe every time you tried to learn, the advice felt contradictory.
If that’s you, take a breath.
Starting now still counts.
You do not need to “catch up perfectly.” You just need a plan you can stick with. And honestly, that’s often more valuable than trying to make up for lost time with some high-pressure strategy you don’t understand.
The first $10,000 milestone is especially powerful for late starters because it gives you a concrete target that feels reachable. You’re not trying to solve your entire financial life in one move. You’re just building the first strong layer.
A Simple Strategy to Reach $10,000 Faster
If your goal is to get to the first $10,000 milestone without feeling overwhelmed, focus on these basics.
1. Automate your contributions
Set up automatic transfers from checking to your investment account.
Why this helps:
- You don’t have to remember
- You avoid decision fatigue
- You remove temptation to spend the money elsewhere
Automation is one of the most underrated parts of investing math. The math works better when your behavior is consistent.
2. Increase your monthly amount when you can
You don’t have to start big. But whenever your income rises, even by a little, try to raise your contribution.
For example:
- Get a raise? Add $25 or $50 per month.
- Pay off a bill? Redirect part of that payment into investing.
- Cut one unnecessary subscription? Turn that into your investment habit.
Small upgrades can shave months off your timeline.
3. Keep fees low
Before you invest, check what you’re paying.
A simple rule:
- Know the fee
- Understand why it exists
- Make sure it’s worth it
You don’t need zero fees at all costs. You just need to avoid paying for things you don’t understand.
4. Stay diversified
Diversification means not putting all your eggs in one basket.
In plain English, it means spreading your money across different types of investments so one bad move doesn’t wreck everything. For beginners, that often means using broad index funds or diversified funds instead of trying to pick individual winners.
This isn’t about chasing excitement. It’s about lowering unnecessary risk.
5. Give it time
This part is boring, but it’s true: time is a major part of the formula.
The market will wobble. Some months will feel slow. You might wonder whether you’re doing enough.
That’s normal.
The point isn’t to feel motivated every day. The point is to keep the system running.
What a “Good” Timeline Looks Like
People often ask, “How fast should I get to $10,000?”
The honest answer is: it depends on what you can comfortably invest.
Here’s a rough way to think about it:
- $50/month: slow but meaningful, especially if you’re starting from zero
- $100/month: solid first step for many beginners
- $250/month: a strong pace that can build momentum
- $500/month or more: can shorten the timeline dramatically
The right timeline is the one that doesn’t make your life harder.
If investing makes you anxious because you’ve stretched too thin, the plan is too aggressive. The best plan is the one you can repeat.
A Real-Life Example: “I Thought I Needed More Money”
Imagine Sam, 34, works full time, makes around $58,000, and has spent years thinking investing was something he’d start “once he had more money.”
He finally tries a first $10,000 milestone calculator and realizes something surprising: he doesn’t need a giant lump sum to begin. If he invests $150 per month and adds a one-time $1,000 bonus from work, he can make real progress without changing his whole life.
That’s the shift.
The calculator doesn’t magically create money. It gives Sam a clearer view of what’s possible. And once he sees the timeline, the goal stops feeling like a vague dream and starts feeling like a plan.
That’s the power of investing math done right.
Common Mistakes to Avoid
When people first start working toward $10,000, they often get tripped up by a few things.
Chasing unrealistic returns
If a calculator shows a huge growth rate, be careful. It may look exciting, but it can set you up for disappointment.
Ignoring fees
Even small fees deserve attention. They don’t always seem like much, but they can quietly eat into progress.
Investing inconsistently
Skipping contributions all the time slows momentum. Regularity matters.
Panicking during market dips
Markets go up and down. A dip doesn’t automatically mean something is wrong.
Comparing your path to someone else’s
Your income, debt, expenses, and life stage are yours. Their timeline isn’t your timeline.
How to Use the Milestone to Stay Motivated
The first $10,000 isn’t just a financial target. It’s a psychological one.
Try these simple ideas to keep yourself on track:
- Track your progress monthly
- Celebrate every $1,000
- Adjust your contributions when income changes
- Remind yourself why you started
- Keep the goal visible somewhere simple, like a note on your phone
The goal is to make investing feel less like a mystery and more like a habit.
If you’re using the deep dive the first $10,000 milestone calculator alongside your own savings plan, you’re not just guessing anymore. You’re building a roadmap.
The Bottom Line
The first $10,000 milestone is important because it turns investing from a scary concept into something tangible. It shows you how savings, time, compounding, and consistency work together. And once you understand that, the whole process becomes a lot less intimidating.
You don’t need perfect timing. You don’t need advanced math skills. You don’t need to know every market term.
You just need a plan, a realistic contribution, and a little patience.
That’s the real value of investing math: it helps you make decisions with confidence instead of fear.
So if you’ve been waiting for the “right time” to start, consider this your sign. Start where you are, use the tools that make the numbers easier to understand, and let the first $10,000 become your proof that this is possible.
Not easy. Not instant. But absolutely possible.
Leave a Reply